Why should I choose AnalystNotes?
Simply put: AnalystNotes offers the best value and the best product available to help you pass your exams.
Basic Question 3 of 10
Consider a four-year, 5% annual coupon payment bond. Its yield to maturity is 10% and its price is 84.16 per 100 of par value.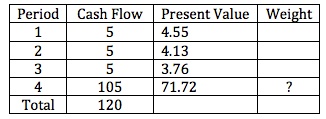
B. 0.7172
C. 0.8522
To calculate Macaulay duration, what should be the weight of the last payment of 105?
A. 0.8750
B. 0.7172
C. 0.8522
User Contributed Comments 1
| User | Comment |
|---|---|
| janglejuic | 71.72 / (4.55+4.13+3.76+71.72) |
I am happy to say that I passed! Your study notes certainly helped prepare me for what was the most difficult exam I had ever taken.
Andrea Schildbach
Learning Outcome Statements
describe the relationships among a bond's holding period return, its Macaulay duration, and the investment horizon
define, calculate, and interpret Macaulay duration
CFA® 2026 Level I Curriculum, Volume 4, Module 10.